The hidden cost of ignoring pension performance
Many professionals residing in County Meath make the daily commute to Dublin from growing residential hubs such as Navan, Ashbourne, and Dunboyne. Balancing a demanding career in the city with family life in Meath often leaves little time for personal financial administration. Consequently, legacy workplace pension schemes from previous employers are frequently left unmanaged, sitting in default investment strategies that may no longer align with the risk profile or retirement timeline of the holder. For those seeking professional pension advice in county meath, understanding the quiet erosion of these dormant funds is a critical starting point.
When left unattended, stagnant fund growth fails to keep pace with the rising cost of living. According to data published by the Central Statistics Office of Ireland in 2024, consumer price inflation directly diminishes the purchasing power of static cash reserves and low-yield investments over time. If a pension fund achieves an annual growth rate of only 1.5% while inflation hovers around 2.5%, the real value of that retirement nest egg actually declines year on year. Commuting professionals often overlook this silent depreciation because the nominal balance on their annual statements appears stable or slightly positive, masking the loss of actual purchasing power.
Without active management, asset allocations within older pension schemes can also become misaligned. A fund selected fifteen years ago might have transitioned automatically into low-risk, low-yield bonds as part of a default lifestyle strategy, even though the individual plans to work for another decade. This premature de-risking prevents the portfolio from benefiting from compound equity growth during key wealth-accumulation years, leaving the professional with a significantly smaller fund than their career success should dictate.
How management fees eat into retirement nest eggs
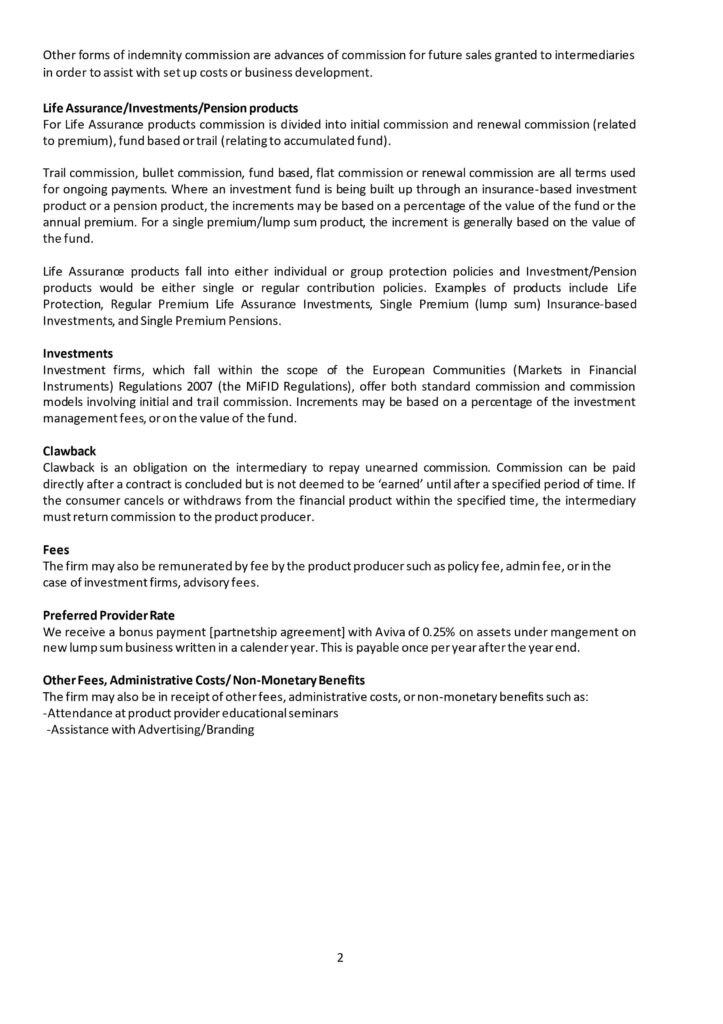
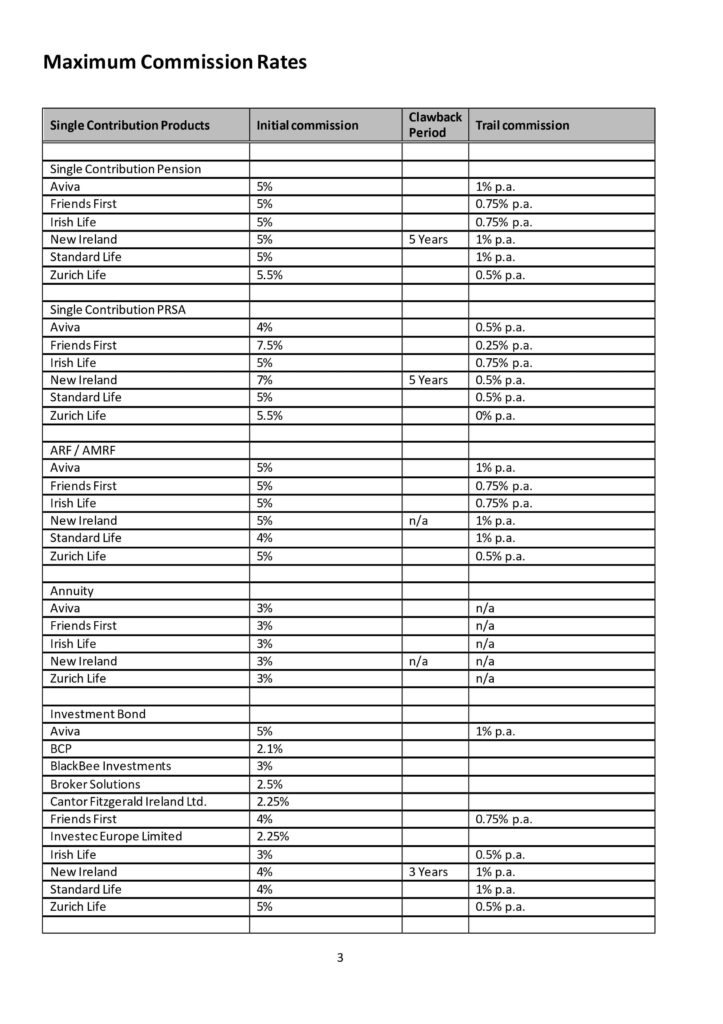
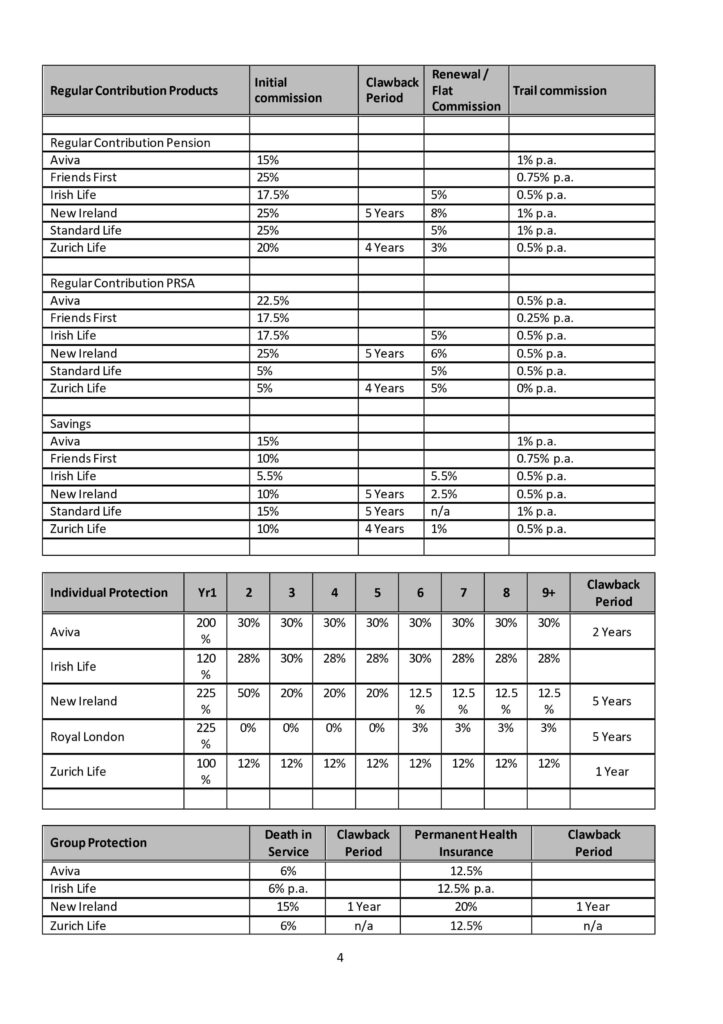
Annual management charges, administration fees, and policy charges can quietly erode a significant portion of a retirement fund over a ten or twenty year horizon. Many older pension schemes carry high legacy fee structures that are significantly more expensive than modern alternatives. A professional assessment through pension reviews can identify these charges and highlight where capital is being lost unnecessarily to outdated provider terms.
To illustrate the compounding effect of these charges, consider a professional with a €150,000 retirement pot that has twenty years remaining until retirement. If the underlying investments grow at an average rate of 5% per annum before fees, the final balance will vary dramatically depending on the annual management charge. Under a modern, optimized fee structure charging 0.75% annually, the net growth rate is 4.25%, resulting in a projected final fund value of approximately €344,830. However, if the legacy scheme charges a 1.5% annual management fee, the net growth rate drops to 3.5%, yielding a final fund value of approximately €298,460. This difference of more than €46,370 represents wealth lost entirely to administration fees, money that could otherwise fund a more comfortable retirement lifestyle.
In addition to annual management charges, some older policies apply entry fees or low allocation rates on contributions, meaning only 95% to 98% of the invested money actually goes toward purchasing fund units. Identifying these hidden costs early allows professionals to restructure their assets, eliminate unnecessary intermediary charges, and preserve more of their hard-earned capital for retirement.
Consolidating multiple pension pots from a career journey
Modern career paths rarely involve staying with a single employer for life. Mid-career professionals in Meath frequently transition between roles, leaving behind a trail of dormant pension pots with different providers. Managing multiple distinct schemes creates significant administrative complexity, making it difficult to assess overall asset allocation, total fee exposure, and retirement readiness.
Consolidating these disparate pots into a single, modern pension structure simplifies retirement planning. Instead of tracking multiple login portals, paper statements, and varying fee schedules, professionals can view their entire retirement portfolio in one centralized location. This consolidation also allows for a unified investment strategy, ensuring that all assets are working toward the same risk and return objectives rather than competing against one another in uncoordinated funds. It also makes it easier to adjust the portfolio’s risk profile as retirement approaches.
The process of combining pensions begins with tracing old schemes, which often requires locating previous employer details and policy numbers. A structured evaluation via pension reviews helps determine if transferring these funds is financially advantageous, ensuring that valuable benefits, such as guaranteed annuity rates or specific tax-free lump sum entitlements, are not lost during the transition. Once analyzed, the assets can be systematically transferred into a single, high-performing account designed for long-term growth and transparent fee reporting.
Finding personalized pension advice in County Meath
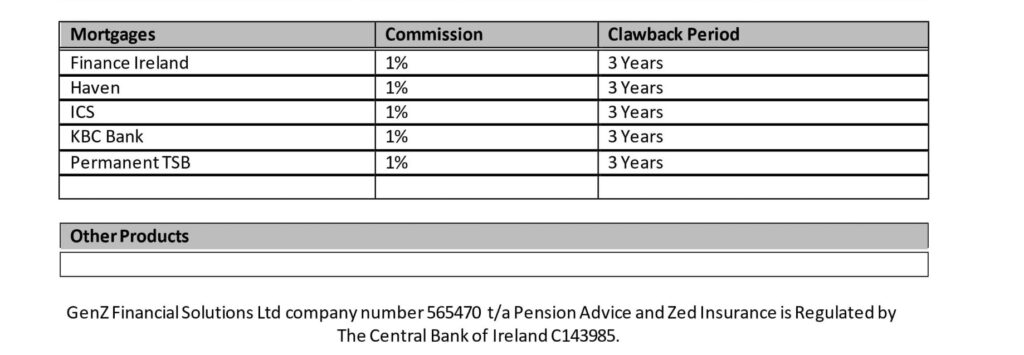
Generic online tools and calculators offer a standardized approach to retirement planning, but they fail to account for the unique financial realities of individual careers. For professionals seeking pension advice in county meath, relying on these automated systems or the tied agents at local high street banks can lead to costly inefficiencies. Tied agents are legally restricted to promoting the proprietary financial products of a single institution. This limitation prevents them from comparing the wider market, which often results in higher management fees and restricted fund selections.
In contrast, independent pension brokers evaluate the entire Irish marketplace, including major providers like Zurich, Aviva, Standard Life, and Irish Life. According to a report by the Competition and Consumer Protection Commission (CCPC), comparing charges across different providers can save savers thousands of euros over the lifetime of a pension. For example, a professional with a 250,000 euro pension pot could lose over 37,000 euros over fifteen years if paying an annual management charge of 1.5 percent instead of a competitive 0.75 percent rate.
An independent advisor assesses an individual’s specific risk tolerance, current career stage, and long-term objectives to construct a diversified portfolio. This personalized approach ensures that investment allocations align precisely with the client’s comfort level, avoiding the cookie-cutter portfolios often recommended by retail banks. Meath professionals can begin this tailored evaluation process by visiting https://www.pensionadvice.ie/contact to connect with an independent specialist.
Preparing your retirement strategy as you approach your fifties
As professionals enter their fifties, the primary focus of retirement planning shifts from aggressive wealth accumulation to strategic capital preservation. Failing to adjust an investment portfolio during this critical decade can expose decades of accumulated savings to sudden market volatility. According to research published by the Economic and Social Research Institute (ESRI), market downturns occurring within five years of retirement have a disproportionately damaging impact on the final fund value, a concept known as sequencing risk.
To mitigate this risk, senior professionals must transition their assets through a process called lifestyling. This strategy automatically and gradually reallocates capital from high-risk equities into more stable, fixed-income assets and cash equivalents. For instance, a typical transition plan might reduce equity exposure from 80 percent down to 30 percent over a ten-year period, redirecting those funds into government bonds and cash. A structured transition ensures that the core retirement fund is protected from sudden market corrections while still maintaining a portion of the portfolio in growth-oriented assets to combat inflation.
Additionally, professionals in their fifties may want to explore options for accessing their benefits before the standard retirement age. Depending on the pension structure, early retirement options may be accessible from age fifty onwards, allowing for greater flexibility in career transitions. Detailed guidance on these structured pathways is available at https://www.pensionadvice.ie/services/early-retirement.
Managing UK pension transfers for Meath residents
Many professionals residing in Meath have spent portions of their careers working in the United Kingdom, leaving behind one or more UK pension pots. Managing these offshore assets requires careful navigation of both British and Irish tax systems. Transferring a UK pension to an Irish scheme involves moving the funds into a Qualifying Recognised Overseas Pension Scheme (QROPS). This status is critical, as transferring funds to a non-compliant scheme can trigger an unauthorized payment charge of up to 55 percent from HM Revenue and Customs (HMRC).
According to guidelines updated by HMRC in 2024, the transfer process requires a formal Cash Equivalent Transfer Value (CETV) assessment from the UK provider. Once this valuation is established, the funds must be converted from sterling to euros, exposing the transfer to currency exchange fluctuations. Working with an experienced advisor helps mitigate these exchange risks and ensures compliance with the strict lifetime allowance and transfer limits set by both jurisdictions.
Additionally, under current rules, transfers to a QROPS within the European Economic Area (EEA) are generally exempt from the 25 percent overseas transfer charge, provided the member is resident in an EEA country like Ireland at the time of the transfer. Properly executed transfers consolidate retirement wealth into a single, manageable Irish scheme, reducing administrative overhead and simplifying long-term tax planning. Residents seeking to consolidate their cross-border assets can access specialist assistance at https://www.pensionadvice.ie/services/uk-pension-transfers.
Frequently asked questions
How do I know if my pension fees are too high?
Many older pension schemes carry high annual management charges and allocation fees that eat into your growth. A comprehensive review of your policy documents can identify these hidden costs and help you switch to a more cost-effective modern alternative.
Can I combine pensions from different employers in Ireland?
Yes, you can consolidate multiple dormant pension pots from previous jobs into a single personal retirement bond or PRSA. This makes your retirement savings much easier to track, manage, and optimize for growth.
Where can I get independent pension advice in County Meath?
You can access impartial advice by contacting an independent financial advisor who has access to the entire Irish market. This ensures you receive unbiased recommendations tailored to your goals rather than being restricted to a single bank’s products.
Can I access my pension early if I live in Meath?
In many cases, occupational and personal pensions can be accessed from age 50 or 55 depending on the specific rules of your scheme. Speaking with a specialist will help you understand your options for early retirement and any associated tax implications.